The short answer
Lists of states that don't tax military retirement can make this look like a yes-or-no question. It isn't. Reading WheelsUp's income-tax files for all 50 states, captured July 18–19, 2026, the states fall into five groups:
| Treatment | States | Count |
|---|---|---|
| No broad individual income tax | Alaska, Florida, Nevada, New Hampshire, South Dakota, Tennessee, Texas, Washington, Wyoming | 9 |
| Excluded in full | Alabama, Arizona, Arkansas, Connecticut, Hawaii, Illinois, Indiana, Iowa, Kansas, Louisiana, Maine, Massachusetts, Michigan, Minnesota, Mississippi, Missouri, Nebraska, New Jersey, New York, North Dakota, Ohio, Oklahoma, Pennsylvania, Rhode Island, South Carolina, Utah, West Virginia, Wisconsin | 28 |
| Excluded in full, if you meet conditions | North Carolina, Vermont | 2 |
| Partly excluded | California, Colorado, Delaware, Georgia, Idaho, Kentucky, Maryland, New Mexico, Virginia | 9 |
| Taxed, with narrow relief | Montana, Oregon | 2 |
Every state that taxes income has some rule for military retired pay — but the details decide whether it reaches you. In the partial states it stops at a cap or an age line. In Montana it depends on in-state earned income and when you became a resident. In Oregon it reaches only service before October 1, 1991, so a career that started after that date gets none.
Washington, D.C. isn't covered. Each row below names the state law its file relies on.
No broad individual income tax (9 states)
In these states there is no state tax for military retired pay to be excluded from — the reason is the absence of the tax, not a military carve-out.
| State | Treatment and limits | Law |
|---|---|---|
| Alaska | No individual income tax. Local governments are barred from taxing individual net income too. | Alaska Stat. §43.20. |
| Florida | No individual income tax. The limit is in the state constitution; changing it takes a statewide amendment vote. | Fla. Const. art. VII, §5(a) |
| Nevada | No individual income tax. The constitution bars a tax on the wages or personal income of natural persons. | Nev. Const. art. 10, §1(9) |
| New Hampshire | No individual income tax. Its interest-and-dividends tax, which never reached pensions, was repealed effective January 1, 2025. | RSA ch. 77, repealed by 2021, 91:189, II |
| South Dakota | No individual income tax. The state says it imposes none; there is no income-tax statute to cite. | South Dakota Dept. of Revenue, individual taxes page |
| Tennessee | No individual income tax. The Hall tax on interest and dividends was repealed for tax years beginning on or after January 1, 2021. | Tenn. Code Ann. §67-2-102 (repealed); Dept. of Revenue guidance HIT-3 |
| Texas | No individual income tax. The constitution bans a tax on individual net incomes. | Tex. Const. art. VIII, §24-a |
| Washington | No general income tax. A narrow capital-gains excise tax exists, and a flat tax on high household incomes, enacted to start January 1, 2028, is being challenged under the state constitution; per our capture, neither reaches ordinary retired pay. | Wash. Const. art. VII, §§1–2; Culliton v. Chase (1933) |
| Wyoming | No individual income tax. The constitution requires any income tax to credit sales, use and property taxes paid. | Wyo. Const. art. 15, §18 |
Excluded in full (28 states)
These states tax income but take military retired pay out of it entirely (Utah does it with an offsetting credit) — by a military-specific rule, or because they exclude government or retirement income generally. Read the limits in each row: some apply only from a recent tax year, and several reach survivor annuities too.
| State | Treatment and limits | Law |
|---|---|---|
| Alabama | Fully exempt. No age, rating or income test. | Ala. Code §40-18-20 |
| Arizona | Fully subtracted from tax year 2021. Earlier years were capped. | Ariz. Rev. Stat. §43-1022 |
| Arkansas | Fully exempt from tax year 2018. Also covers survivor benefits funded by retired pay; claiming it limits use of the general $6,000 retirement exemption. | Ark. Code Ann. §26-51- |
| Connecticut | Fully excluded. A former spouse's share under a divorce order doesn't qualify. | Conn. Gen. Stat. §12-701 |
| Hawaii | Not taxed. Excluded under the general exclusion for pensions paid for past services. | Haw. Rev. Stat. §235-7 |
| Illinois | Not taxed. Illinois subtracts qualified retirement income generally, at any age. | 35 ILCS 5/203 |
| Indiana | Effectively fully deductible for tax years after 2021. A base amount plus 100% of benefits above $6,250; surviving spouses included. | Ind. Code §6-3-2-4 |
| Iowa | Fully excluded. Survivor Benefit Plan payments are excluded too; both are in addition to the general pension exclusion. | Iowa Code §422.7 |
| Kansas | Fully subtracted. No cap and no rating test. | Kan. Stat. Ann. §79-32,117 |
| Louisiana | Fully exempt. Covers income from a federal retirement system. | La. Rev. Stat. §47:44.2 |
| Maine | Fully subtracted from tax year 2016. Includes survivor benefits. | 36 M.R.S. §5122 |
| Massachusetts | Fully excluded. Uniformed-services retired pay, whether or not the retiree paid into the system. | Mass. Gen. Laws ch. 62, §2(a)(2)(E) |
| Michigan | Fully exempt. Separate from Michigan's birth-year rules for civilian pensions. | Mich. Comp. Laws §206.30 |
| Minnesota | Fully subtracted. Not available if you claim the §290.0677 credit for past military service. | Minn. Stat. §290.0132, subd. 21 |
| Mississippi | Not taxed. Excluded as income from a federal retirement system. | Miss. Code Ann. §27-7-15 |
| Missouri | Fully subtracted. No income limit and no age requirement. | Mo. Rev. Stat. §143.121.2 |
| Nebraska | Fully excluded from tax year 2022. Also covers benefits paid to a spouse, former spouse or child and reported on a DoD or OPM Form 1099-R. | Neb. Rev. Stat. §77-2716 |
| New Jersey | Fully excluded. The Division of Taxation says this applies regardless of age or disability status. | N.J. Stat. Ann. §54A:6-26 |
| New York | Fully subtracted. Treated as a federal pension; the separate private-pension cap doesn't apply. | N.Y. Tax Law §612(c)(3) |
| North Dakota | Fully subtracted. Includes benefits paid to a surviving spouse, to the extent included in federal taxable income. | N.D. Cent. Code §57-38- |
| Ohio | Fully deductible. A federal civil-service pension is deductible only for its military-service portion. | Ohio Rev. Code §5747.01 |
| Oklahoma | Fully exempt from tax year 2022. Earlier years were capped. | Okla. Stat. tit. 68, §2358; Okla. Admin. Code §710:50- |
| Pennsylvania | Not taxed. Includes SBP, RCSBP and RSFPP annuities; Thrift Savings Plan payouts are treated differently. | PA Dept. of Revenue guidance under the Tax Reform Code, 72 P.S. Article III |
| Rhode Island | Fully subtracted from tax year 2023. The subtraction can't exceed the pension received that year. | R.I. Gen. Laws §44-30-12 |
| South Carolina | Fully deductible from tax year 2022. A surviving spouse may claim it on the retiree's pay. | S.C. Code Ann. §12-6-1171 |
| Utah | Offset in full by a credit. A non-refundable credit at the state's flat rate on the retired pay in federal AGI; it can't exceed your Utah tax and doesn't carry forward or back. | Utah Code §59-10- |
| West Virginia | Fully exempt from tax year 2018. Includes survivor annuities. | W. Va. Code §11-21-12 |
| Wisconsin | Fully exempt. Includes Survivor Benefit Plan and RSFPP payments. | Wis. Stat. §71.05 |
Excluded in full — if you meet the conditions (2 states)
| State | Treatment and limits | Law |
|---|---|---|
| North Carolina | Fully deductible from tax year 2021 — but only if the retiree served at least 20 years or was medically retired under 10 U.S.C. chapter 61. Survivor Benefit Plan payments follow the same test. | N.C. Gen. Stat. §105-153.5 (S.L. 2021-180) |
| Vermont | Fully excluded at federal AGI of $125,000 or less, from tax year 2025. Phases out between $125,000 and $175,000 and is gone at $175,000 or more; covers SBP income too; you may claim this or the Social Security exemption, not both. | 32 V.S.A. §5811(21), as amended by Act 71 of 2025 |
The North Carolina test is the one to check before you pick it as a destination: a retiree who served under 20 years and wasn't medically retired doesn't get this deduction.
Partly excluded (9 states)
Here the relief is real but capped — by a dollar amount, an age line, or both. Retired pay above the cap is taxed.
| State | Treatment and limits | Law |
|---|---|---|
| California | Up to $20,000 a year excluded, tax years 2025 through 2029 as enacted. Phases out above AGI of $125,000 (single) or $250,000 (joint or surviving spouse); covers SBP payments too. | California's 2025 military retirement income exclusion (2025-26 Budget Act; Revenue and Taxation Code) |
| Colorado | Partly subtracted, under the general pension subtraction. $20,000 a year at ages 55–64; $24,000 at 65 and older. | Colo. Rev. Stat. §39-22- |
| Delaware | Capped exclusion. Under 60: the greater of $2,000 of pensions or $12,500 of military pension. 60 and older: $12,500 of pension and retirement income combined. | 30 Del. C. §1106 |
| Georgia | Capped exclusion. Under 62: $17,500, plus another $17,500 with at least $17,500 of earned income. 62 and older: the general retirement exclusion — $35,000 at 62–64, $65,000 at 65 and older. | Ga. Laws 2022, HB 1064 (the under-62 exclusion; the general exclusion at 62 and older is a separate provision) |
| Idaho | Capped deduction, with conditions. You qualify if classified as disabled, 62 or older, or employed with enough income to have to file a federal return; the cap is tied to the Social Security maximum benefit and reduced by Social Security or railroad retirement benefits received. | Idaho Code §63-3022A |
| Kentucky | Capped exclusion shared with all pension income. $41,110 for tax years beginning on or after January 1, 2026; fully exempt if you retired before January 1, 1998; a larger exclusion, through Schedule P, in proportion to service before that date. | Ky. Rev. Stat. §141.019 |
| Maryland | Capped subtraction. $20,000 if you are 55 or older on the last day of the tax year; $12,500 if under 55. | Md. Code, Tax-General §10-207(q) |
| New Mexico | Capped exemption. $30,000 for tax years 2024 onward. | NMSA 1978, §7-2-5.13 |
| Virginia | Capped subtraction. $40,000 for tax years from 2025; no age limit from tax year 2024. | Va. Code §58.1- |
Taxed, with narrow relief (2 states)
| State | Treatment and limits | Law |
|---|---|---|
| Montana | Taxed, apart from a limited subtraction. Subtract the lesser of your Montana-source wage income or 50% of your military retirement income, and up to 50% of military survivor benefits — only if you became a resident on or after June 30, 2023, or were a resident before receiving retired pay and stayed; for 5 consecutive years, and not if you claimed it before becoming a nonresident. The Department of Revenue describes the program as ending in tax year 2033. | Mont. Code Ann. §15-30- |
| Oregon | Taxed, except the share earned before October 1, 1991. The subtraction is prorated by months of service before that date; a career entirely after it gets none. | Or. Rev. Stat. §316.680 |
Montana's subtraction depends on in-state earned income. A retiree living on retired pay alone, with no Montana wages, business or farm income, gets nothing from it however large the pension.
These laws move — what was pending when we captured them
Several states were mid-change at capture. None of the following is current law unless it says so:
- Delaware. SB 219, which would raise the military pension exclusion in steps from 2027, had passed both chambers and was awaiting the governor. It was not law at capture. Two earlier bills, SB 201 and HB 108, had not passed.
- New Mexico. SB-116, from the 2026 session, would remove the cap for tax years from 2027. The latest status in our file is dated January 30, 2026, so check whether it passed.
- Idaho. SB 1428 (2024), which would have exempted retired pay regardless of age or disability, passed the Senate and died in a House committee. It is not law.
- California. The exclusion runs through tax year 2029 as currently enacted.
- Washington. The flat tax on high household incomes, scheduled for 2028, was under constitutional challenge.
- Colorado. Some secondary sources describe a separate military subtraction for retirees under 55; our capture couldn't confirm it against the statute, so it isn't in the table. If you are under 55, ask the Colorado Department of Revenue.
Confirm with the state's revenue department before you rely on any row, and check which tax year a rule applies to — several of these took their current form in tax year 2021 or later.
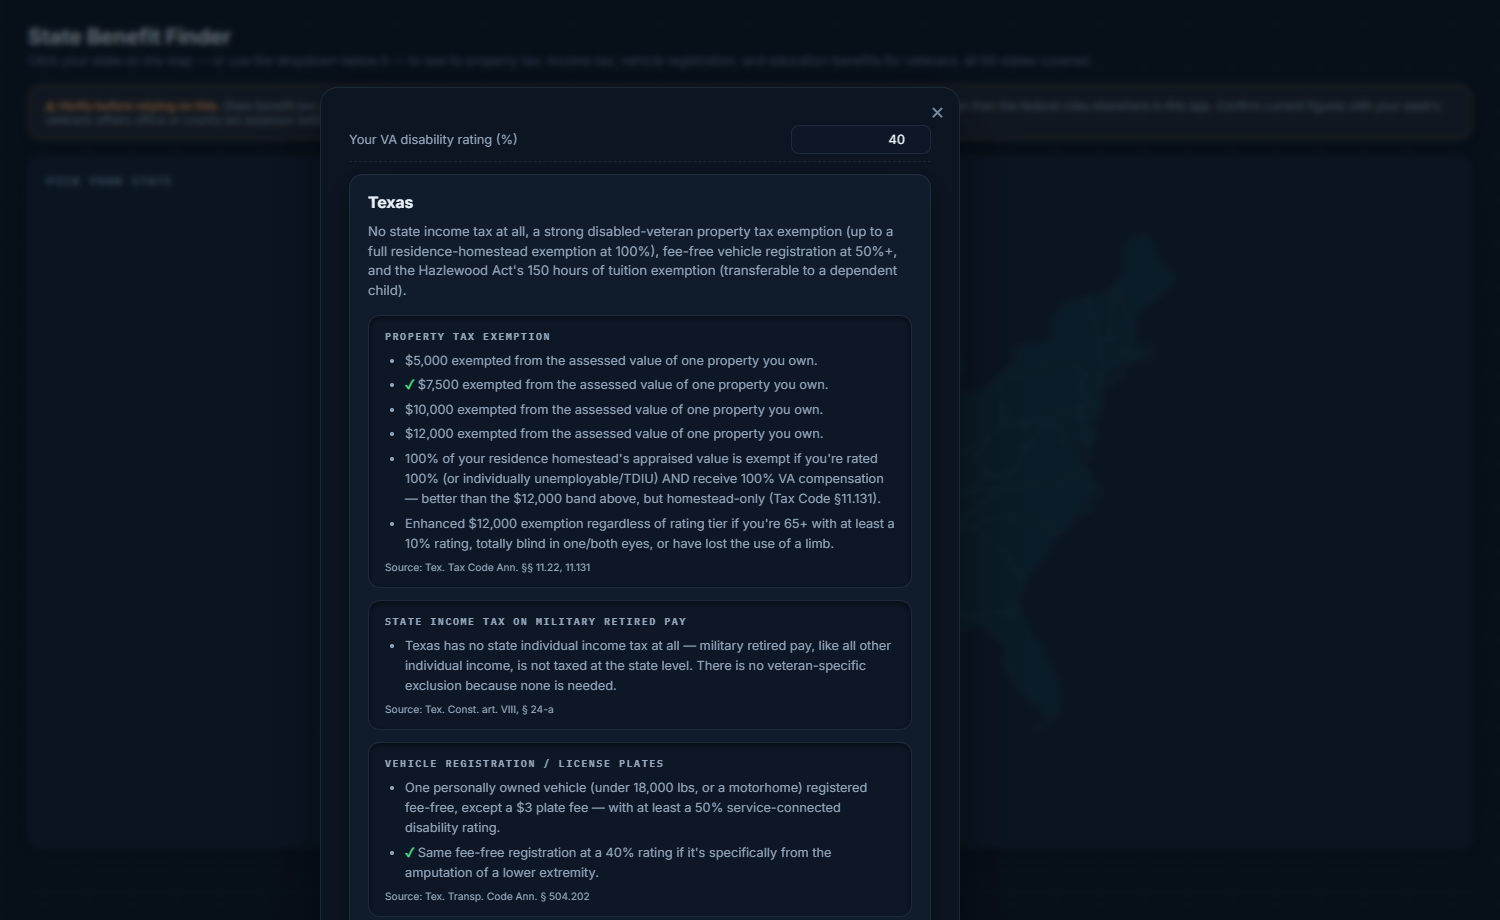
WheelsUp's State Benefit Finder (a Pro tool) opens any of the 50 states from a map or a list and shows how it treats military retired pay beside its property-tax, vehicle and education benefits, each with the law or official source it rests on — and marks the rating-based items your VA rating meets.
The short checklist
- Find your state's row and note the law it rests on.
- Check every condition — age, years of service, income, and when you became a resident.
- Check the tax year a rule starts or ends in; several are recent and at least one has an end date.
- Ask separately about survivor annuities and Thrift Savings Plan withdrawals — states don't always treat them like retired pay.
- Confirm with the state's revenue department before choosing where to live on the strength of this table.
- Recheck every year; at capture a Delaware bill was awaiting the governor and Washington's new tax was in court.
Sources
Each row cites the state law named in WheelsUp's income-tax file for that state; all 50 files were captured July 18–19, 2026, and record the pending bills above.
- No broad income tax — Alaska Stat. §43.20.290 and the 1980 repeal (Sec. 10, ch. 1, SSSLA 1980); Fla. Const. art. VII, §5(a); Nev. Const. art. 10, §1(9); N.H. RSA ch. 77, repealed by 2021, 91:189, II; South Dakota Department of Revenue, individual taxes; Tenn. Code Ann. §67-2-102 (repealed) and Department of Revenue guidance HIT-3; Tex. Const. art. VIII, §24-a; Wash. Const. art. VII, §§1–2 and Culliton v. Chase, 174 Wash. 363 (1933); Wyo. Const. art. 15, §18
- Excluded in full — Ala. Code §40-18-20; Ariz. Rev. Stat. §43-1022(26); Ark. Code Ann. §26-51-307(e)–(f) (Act 141 of 2017); Conn. Gen. Stat. §12-701(a)(20)(B)(xvi); Haw. Rev. Stat. §235-7(a)(3); 35 ILCS 5/203(a)(2)(F); Ind. Code §6-3-2-4; Iowa Code §422.7(20)–(21); Kan. Stat. Ann. §79-32,117(c)(vii); La. Rev. Stat. §47:44.2; 36 M.R.S. §5122(2)(M-2); Mass. Gen. Laws ch. 62, §2(a)(2)(E); Mich. Comp. Laws §206.30(1)(f)(i); Minn. Stat. §290.0132, subd. 21, and §290.0677; Miss. Code Ann. §27-7-15(4)(k); Mo. Rev. Stat. §143.121.2(12); Neb. Rev. Stat. §77-2716(15); N.J. Stat. Ann. §54A:6-26; N.Y. Tax Law §612(c)(3)(i)–(ii); N.D. Cent. Code §57-38-30.3(2)(r); Ohio Rev. Code §5747.01(A)(23); Okla. Stat. tit. 68, §2358 and Okla. Admin. Code §710:50-15-49(g); Pennsylvania Department of Revenue, Military Pay for PA Personal Income Tax Purposes (72 P.S. Article III); R.I. Gen. Laws §44-30-12(c)(11); S.C. Code Ann. §12-6-1171; Utah Code §59-10-1043 and §59-10-104(2); W. Va. Code §11-21-12(c)(7)(C); Wis. Stat. §71.05(1)(am), (an)
- Excluded in full, with conditions — N.C. Gen. Stat. §105-153.5 (S.L. 2021-180); 32 V.S.A. §5811(21), as amended by Act 71 of 2025
- Partly excluded — California's 2025 military retirement income exclusion (2025-26 Budget Act); Colo. Rev. Stat. §39-22-104(4); 30 Del. C. §1106(b)(3); Ga. Laws 2022, HB 1064; Idaho Code §63-3022A; Ky. Rev. Stat. §141.019(1)(g); Md. Code, Tax-General §10-207(q); NMSA 1978, §7-2-5.13; Va. Code §58.1-322.02
- Taxed, with narrow relief — Mont. Code Ann. §15-30-2120(3)(n), (8), (9); Or. Rev. Stat. §316.680(1)(e)
Spot an error? Tell us — citations are the product here.
Where you live decides what you keep. WheelsUp back-plans every deadline from your actual date and branch, with the citation attached to each card.