The whole formula, in one line
Gross monthly retired pay is two numbers multiplied together:
retired pay base × multiplier
- The retired pay base comes from 10 U.S.C. §1407. Under §1407(b), it is “the person's high-three average determined under subsection (c) or (d).”
- The multiplier comes from 10 U.S.C. §1409: a rate per year times your years of creditable service. The rate is 2½ under the general rule and 2 for the Blended Retirement System — the statute's modernized retirement system.
The catch is not the multiplication. It is getting each input right — and three easy errors are using the wrong pay (your current rate instead of an average), the wrong years (rounded instead of counted by month), or the wrong system. Which system you are under is its own question, covered in our REDUX vs. High-3 vs. BRS guide. This page is the arithmetic.
Step 1: your High-3 is an average, not your last paycheck
§1407(c)(1) defines the high-three average as “the total amount of monthly basic pay to which the member was entitled for the 36 months (whether or not consecutive) out of all the months of active service of the member for which the monthly basic pay to which the member was entitled was the highest, divided by 36.”
Three things in that sentence do the work:
- Basic pay only. The statute counts monthly basic pay — nothing else goes into the average.
- Your highest 36 months, whether or not they were consecutive. Often they are the last three years, because basic pay rises with years of service and the tables change over time; but the rule is highest, not last.
- Divided by 36. A raise or a longevity step that arrives late in your career counts only for the months you were actually paid at it.
That last point is why your High-3 usually sits below your final monthly basic pay.
Step 2: reading the 2026 basic pay tables
DFAS publishes basic pay as tables by pay grade and cumulative years of service; the 2026 tables took effect January 1, 2026. The columns run from 2 or less through Over 2, Over 3, Over 4, and then two-year steps up to Over 40. Your monthly rate is where your grade's row meets your years-of-service column.
A few rows from the 2026 tables, at the columns most retirees pass through (monthly basic pay, effective January 1, 2026):
| Grade (2026) | Over 20 | Over 22 |
|---|---|---|
| E-7 | $6,245.70 | $6,475.20 |
| E-8 | $6,995.40 | $7,308.30 |
| E-9 | $8,105.10 | $8,423.10 |
| O-3E | $9,609.60 | $9,609.60 |
For reference, the 2026 E-7 rate at Over 18 is $6,177.30. O-3E is the 2026 table for officers in grades O-1 through O-3 with more than four years of creditable service, as that table's heading describes it — and its Note 3 counts only active service as an enlisted member or as a warrant officer toward those years. Its rate stops rising after Over 18, so both columns above are identical.
Two cautions. A 2026 table is only the input for months paid in 2026 — your 36 months will usually span two or three years' tables. And the right column changes as you complete years of service, so a High-3 usually mixes more than one column as well as more than one year.
Step 3: count your years of service by the month
§1409(c) defines years of creditable service as the number of years creditable in computing retired pay, “including 1/12 of a year for each full month of service”. Partial years count, month by month:
- 20 years and 0 months = 20 years.
- 20 years and 7 months = 20 7/12 years, about 20.583.
- 20 years, 7 months and 20 days = still 20 7/12 years — only full months count.
Guard and Reserve retirement counts service differently: under 10 U.S.C. §12733, years of service for that retired pay are computed by “dividing 360 into the sum of the following” — days of active service, certain full-time duty, and credited points. See our Guard and Reserve retirement guide for that calculation.
Step 4: the multiplier — 2.5% or 2.0% a year
The general rule, §1409(b)(1): the percentage is the product of 2½ and your years of creditable service.
The Blended Retirement System, §1409(b)(4): for a member who first becomes a member of the uniformed services on or after January 1, 2018, or who made the BRS election — a “full TSP member” — the statute substitutes 2 for 2½.
| Years | High-3 rule (2.5 × years) | BRS (2.0 × years) |
|---|---|---|
| 20 | 50% | 40% |
| 22 | 55% | 44% |
| 24 | 60% | 48% |
| 26 | 65% | 52% |
| 30 | 75% | 60% |
Past 30 years. For members retiring after December 31, 2006 with more than 30 years, §1409(b)(3) sets the percentage as 75 plus 2½ for each year over 30 — which works out to the same 2½ × years. BRS substitutes 60 for 75 and 2 for 2½, which works out to 2 × years. There is no 75% ceiling in that arithmetic for an active-duty retiree today. The REDUX guide works through that algebra.
REDUX starts from the 2½ rule and, under §1409(b)(2), subtracts 1 percentage point for each full year short of 30 (and 1/12 of a point for each month), for a member who joined after July 31, 1986, took the bonus, has under 30 years and is under 62 at retirement. The REDUX guide covers what that costs and what happens at 62.
A worked example, to the cent
Worked example (illustrative inputs). An E-7 retires with exactly 22 years of creditable service. To keep the arithmetic visible, assume every month in the High-3 was paid at 2026 rates: the highest 36 months are 12 months at the 2026 E-7 Over 18 rate of $6,177.30 and 24 months at the 2026 Over 20 rate of $6,245.70.
- High-3: (12 × $6,177.30) + (24 × $6,245.70) = $74,127.60 + $149,896.80 = $224,024.40. Divided by 36 = $6,222.90.
- Years: 22 years, 0 months = 22.
- Multiplier: High-3 rule 2.5 × 22 = 55%. BRS 2.0 × 22 = 44%.
- Gross monthly retired pay: High-3 rule $6,222.90 × 55% = $3,422.60. BRS $6,222.90 × 44% = $2,738.08.
- The difference: $684.52 a month, or $8,214.24 a year, before any cost-of-living adjustment.
A real High-3 mixes more than one year's pay table, so the actual figure for this member would differ. The method would not. The BRS line applies the 2.0 multiplier to the same inputs for comparison only.
Note what the BRS comparison leaves out: BRS members also have government contributions made to their TSP accounts during service — 5 U.S.C. §8440e caps them at 5 percent of basic pay per pay period — which the 2.0 multiplier does not capture. Compare the whole package, not just the pension line — our TSP guide covers that side.
After the formula: what actually reaches your account
Gross retired pay is where the calculation starts, not where it ends. In WheelsUp's estimator the gross figure is followed by the things that can sit between it and your deposit — a Survivor Benefit Plan premium, a VA waiver when you also receive disability compensation and do not qualify for concurrent receipt (see our CRDP guide), federal and state tax, and a TRICARE premium. And every year after that, the amount is adjusted under 10 U.S.C. §1401a(b): the full increase under (b)(2) for the High-3 rule and — under (b)(5) — for BRS, and the reduced (b)(3) increase for REDUX electees.
WheelsUp's Retirement Pay estimator does the multiplication in the open — the High-3 average you enter, your years from your own dates, the multiplier for High-3, BRS or REDUX — and then shows each deduction as its own step, so you can see where the gross figure goes.
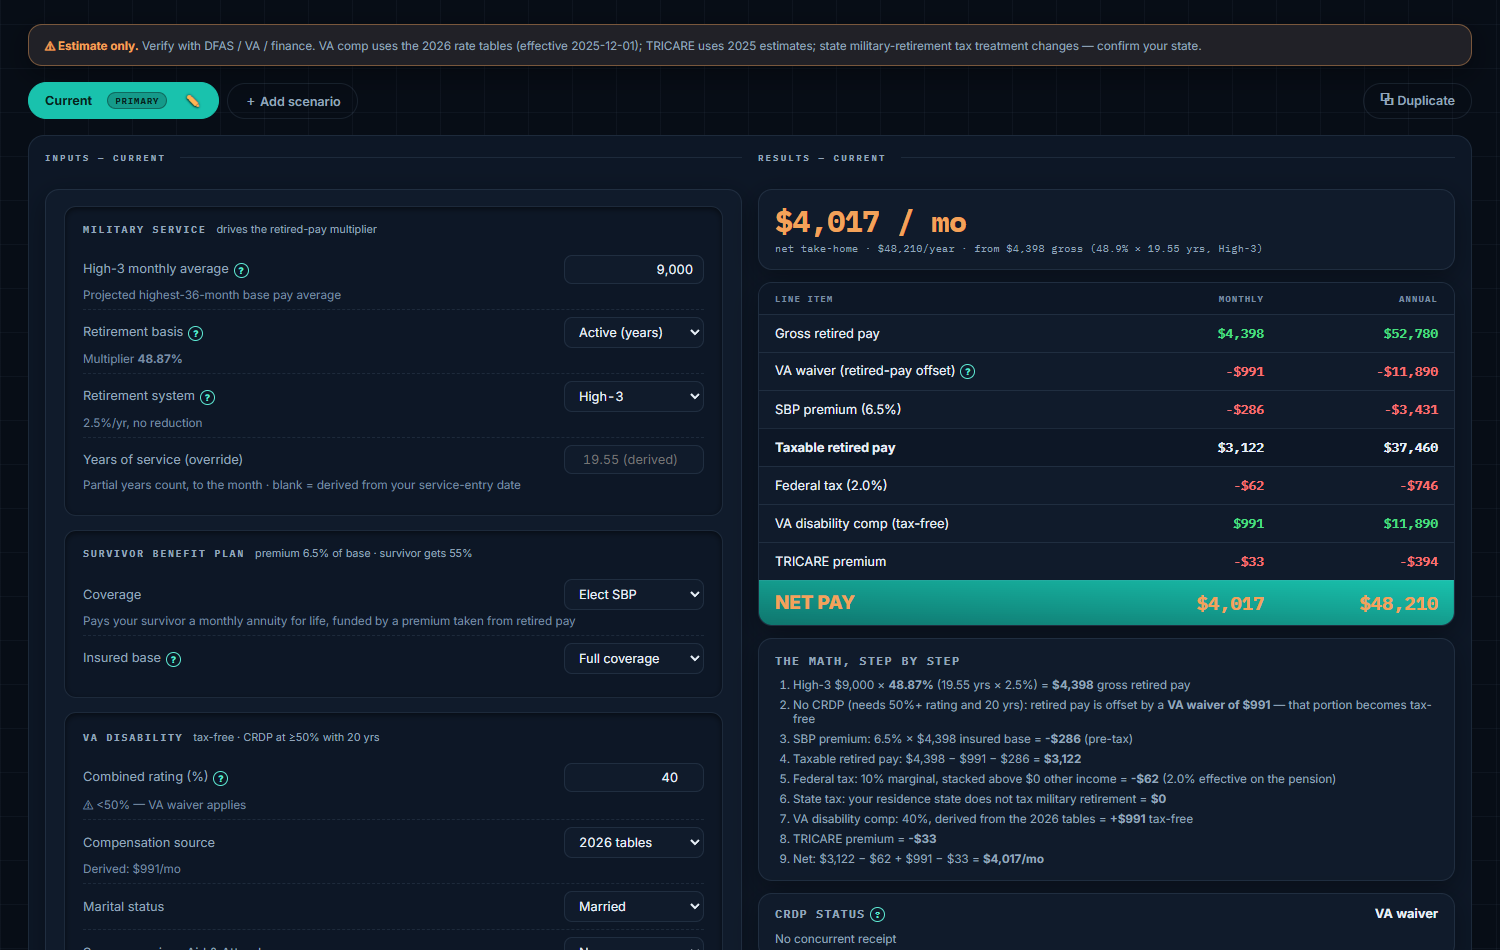
How the Retirement Pay tool (Pro) works:
- You enter your High-3 monthly average and choose High-3, BRS or REDUX.
- Years of service come from your service start and retirement dates, counted as an exact fraction of a year rather than in whole months, or you can override them; Guard and Reserve members can use retirement points divided by 360 instead.
- The multiplier follows §1409: 2.5% or 2.0% a year, the REDUX reduction when it applies, and no 75% cap for an active-duty retiree past 30 years.
- A step-by-step math list shows the multiplication, the SBP premium, any VA waiver or concurrent receipt, taxable pay, federal and state tax, TRICARE and the net — with a cited sources footer.
- Named scenarios sit side by side, so you can compare systems, High-3 or years-of-service assumptions, or SBP choices directly.
If your High-3 is still in the future, the Pay & COLA Projector (also Pro) projects basic-pay raises at a rate you choose to estimate it, and projects COLA growth after you retire.
The short checklist
- Confirm your retirement system — High-3 rule, BRS or REDUX — before you trust any number.
- List your highest 36 months of basic pay from your pay records, not from one table.
- Count your service in full years and full months.
- Multiply: 2.5 × years, or 2.0 × years under BRS, or the REDUX-reduced rate.
- Apply it to the High-3, then subtract what will actually come out — SBP, any VA waiver, taxes, TRICARE.
- Confirm with your pay center before you set a retirement date around the result.
Sources
- 10 U.S.C. §1407 — (b) the retired pay base is the high-three average; (c)(1) the highest 36 months of monthly basic pay, whether or not consecutive, divided by 36
- 10 U.S.C. §1409 — (b)(1) 2½ × years of creditable service; (b)(2) the REDUX reduction; (b)(3) the rule above 30 years for members retiring after December 31, 2006; (b)(4) the BRS full-TSP-member substitutions (2 for 2½; 60 percent for 75 percent); (c) years of creditable service including 1/12 of a year per full month
- DFAS, Basic Pay – Enlisted, effective January 1, 2026 — E-7 Over 18 through Over 22; E-8 and E-9 Over 20 and Over 22
- DFAS, Basic Pay – Officers (O-1, O-2 and O-3) with more than 4 years of creditable service, effective January 1, 2026 — O-3E Over 18 through Over 22
- 10 U.S.C. §1401a — (b)(2) the retired-pay increase; (b)(3) the reduced increase for bonus electees; (b)(5) the full increase for modernized-retirement-system participants
- 10 U.S.C. §12733 — years of service for non-regular retired pay, computed by dividing 360 into the sum of creditable days and points
- 5 U.S.C. §8440e — government TSP contributions for full TSP members of the uniformed services, not more than 5 percent of basic pay per pay period
Spot an error? Tell us — citations are the product here.
Your High-3, your years, your system — shown step by step. WheelsUp runs the statute's arithmetic on your own numbers and keeps every deduction visible.