Under FERS: no deposit, no credit
People call it a military buyback. The statute calls it a deposit, and under the Federal Employees Retirement System it is not optional if you want the time to count.
5 U.S.C. §8411(c)(1) allows credit for two kinds of military service:
- (A) service performed before January 1, 1957; and
- (B) service performed after December 31, 1956 and before the separation your annuity is based on — but only “if a deposit (including interest, if any) is made with respect to such period in accordance with section 8422(e)”.
The catch is in (B): for anyone serving today, the time counts under FERS only if the deposit is made. There is no free credit to fall back on.
What the deposit costs
§8422(e)(1)(A) sets the amount at “3 percent of the amount of the basic pay paid under section 204 of title 37 to the employee or Member for each period of military service after December 1956.” Three details in that sentence matter:
- Basic pay actually paid. It is a percentage of the military basic pay you received for the period — not of your civilian salary, and not of today's military pay rates.
- Two years carry different rates. Under §8422(e)(6), service performed from January 1 through December 31, 1999 is charged at 3.25 percent, and service from January 1 through December 31, 2000 at 3.4 percent.
- The pay figure needs evidence. The amount is based on the evidence of basic pay you provide; if OPM finds it insufficient, the payment is based on estimates furnished to OPM by the Secretary of Defense (or the Secretary of Transportation, Commerce, or Health and Human Services, as appropriate) under §8422(e)(4).
You pay it to your employing agency, which remits it to OPM for the retirement fund.
A cap for interrupted civilian careers. §8422(e)(1)(B): if military service interrupted creditable civilian service and you were reemployed under chapter 43 of title 38 on or after August 1, 1990, the deposit may not exceed what would have been withheld from your civilian basic pay had you not served.
Worked example (illustrative figures). A member's records show $250,000 of military basic pay received over their service, of which $30,000 was paid during 1999 and none during 2000.
- 1999 portion: $30,000 × 3.25% = $975.
- Everything else: $220,000 × 3% = $6,600.
- Deposit before any interest: $7,575 — not the $7,500 a flat 3% would suggest.
The interest clock: two years, then compounding
§8422(e)(2) gives you a window. A deposit made more than two years after the later of January 1, 1987, or the date you first became a federal employee following the military service “shall include interest on such amount computed and compounded annually beginning on the date of the expiration of the two-year period.”
Read that in plain terms: pay within two years of starting your federal job and there is no interest. After that, interest compounds every year the deposit remains unpaid.
The rate is not fixed in the FERS section. §8422(e)(2) borrows the rate that applies for the year under §8334(e). That section sets 4 percent a year through 1947 and 3 percent from 1948 through 1984; after that, the rate for each calendar year is “the overall average yield to the Fund during the preceding fiscal year” from certain Treasury obligations. So the rate changes year to year, and nobody can tell you in advance what a late deposit will cost.
One protection: under §8422(e)(7), if your employing agency makes an administrative error in calculating or processing the deposit, the agency may pay any additional interest assessed because of it.
Worked example (illustrative rate). The $7,575 deposit above is paid three full years after the two-year window closed. Assume, only for illustration, a 4% rate in each of those years:
- $7,575 × 1.04 × 1.04 × 1.04 = $8,520.84.
- Interest owed: $945.84 — on top of a deposit that would have cost $7,575 if paid inside the window.
The real rate for each year is the one set under §8334(e)(3) for that year.
The retired-pay catch — and its two exceptions
This is the paragraph that decides whether the deposit helps you at all. §8411(c)(2): if you are awarded retired pay based on a period of military service, “the service of the employee or Member may not include credit for such period of military service unless the retired pay is awarded” either:
- (A) based on a service-connected disability that was (i) incurred in combat with an enemy of the United States, or (ii) caused by an instrumentality of war and incurred in line of duty during a period of war as defined by 38 U.S.C. §1101; or
- (B) under chapter 1223 of title 10 (or its predecessor, chapter 67 as in effect before the Reserve Officer Personnel Management Act) — the Guard and Reserve retirement chapter; confirm with OPM and your finance center that your retired pay is awarded under it.
What that means:
| Your situation | Can the deposit credit the service? |
|---|---|
| No military retired pay (you separated) | Yes — §8411(c)(1)(B), with the deposit. |
| Chapter 1223 (Guard/Reserve) retired pay | Yes — the (c)(2)(B) exception. |
| Retired pay for a combat or instrumentality-of-war disability | Yes — the (c)(2)(A) exception. |
| Other retired pay based on the same service | Not while that retired pay is awarded on that service. §8411(c)(5) refers to members who waive retired pay that is subject to a court order and then credit the service — ask your finance center and OPM how a waiver works in your case. |
A court order follows you. §8411(c)(5): if, after January 1, 1997, you waive retired pay that is subject to a court order served for purposes of 10 U.S.C. §1408, the service can be credited only if you authorize OPM to deduct and withhold from your annuity the amount the former spouse would have received from your retired pay — which OPM then pays to that former spouse.
Two narrower rules in the same subsection: a CSRS military deposit you already made and never took back counts without a new FERS deposit, and you can apply for a refund of the difference (§8411(c)(3)); and if an employee who was awarded military retired pay dies before separating, the survivor annuity counts that military service anyway — service creditable under (c)(1) or (c)(3), with any §8422(e)(5) deposit taken into account — reduced by uniformed-services survivor benefits based on the same period (§8411(c)(4)).
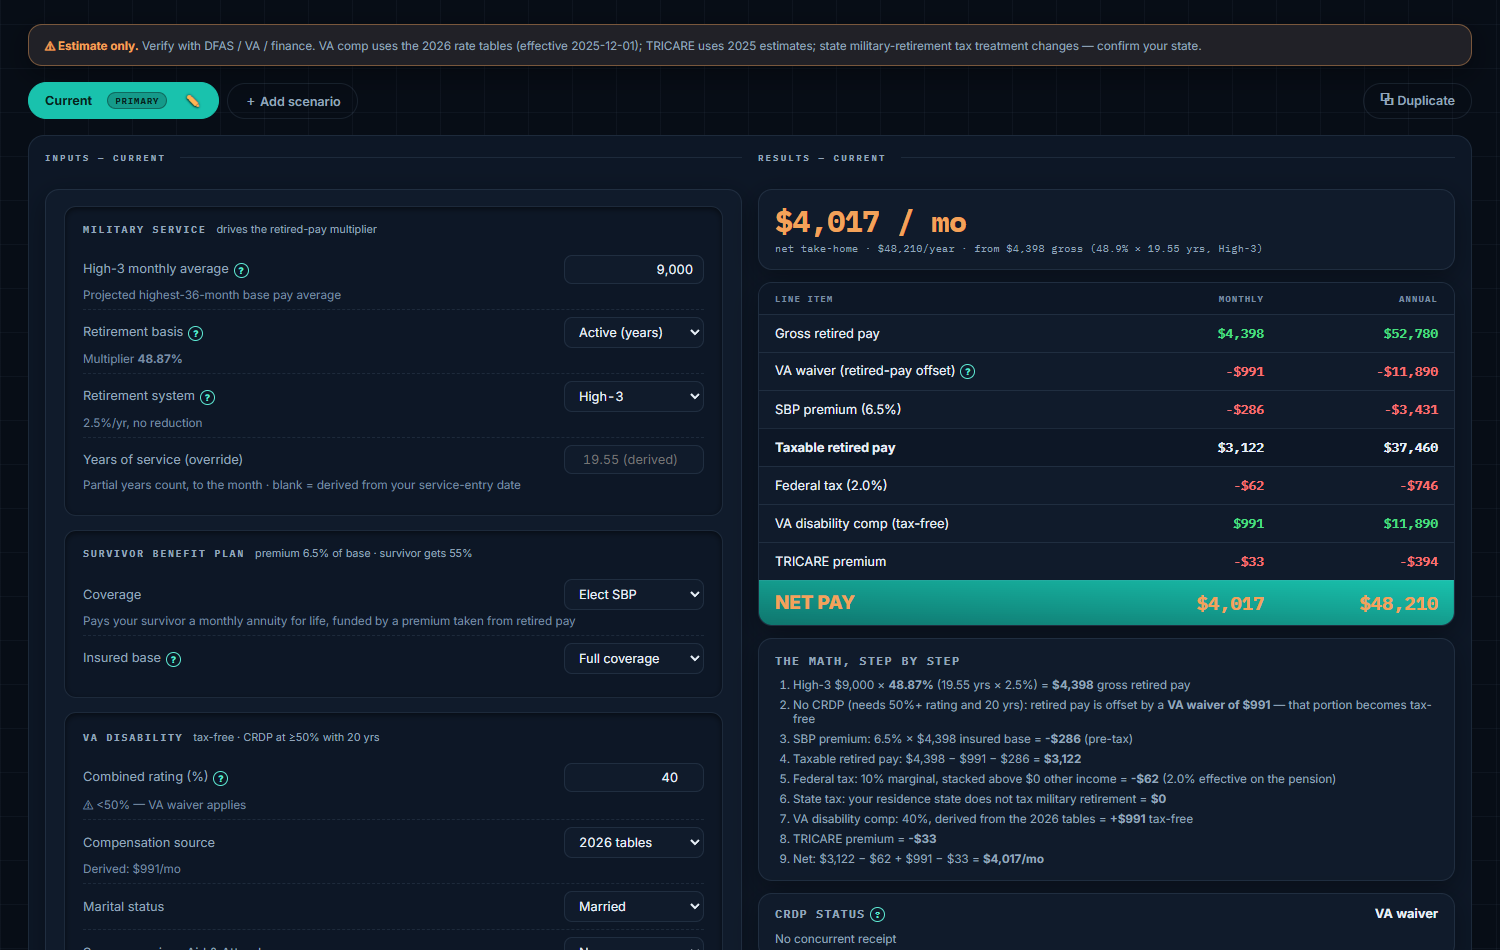
For an active-duty retiree, the buyback is a trade — and WheelsUp's Retirement Pay estimator shows the other side of it: the gross military retired pay in question, step by step, and what survives SBP, any VA waiver and tax.
What a bought year is worth
The deposit buys years of service in the FERS annuity formula. §8415(a): the basic annuity is “1 percent of that individual's average pay multiplied by such individual's total service.”
§8415(i) raises the percentage to 1.1 percent for an employee who retires entitled to an annuity under §8412 and who, at separation, is at least 62 and has completed at least 20 years of service — with exclusions for Congressional employees, dual-status military technicians, law enforcement officers, Supreme Court Police, firefighters, nuclear materials couriers, air traffic controllers and customs and border protection officers.
So each bought year adds roughly 1 percent (or 1.1 percent) of your future federal average pay to every year of your annuity. One interaction to check: under §8415(h), an annuity under §8412(g) or §8413(b) is reduced by five-twelfths of 1 percent for each full month it begins before your 62nd birthday, unless the (h)(2) exception applies.
Worked example (illustrative figures). A federal employee expects an average pay of $90,000 and buys 4 years of military service.
- At 1%: $90,000 × 1% × 4 = $3,600 a year of added annuity.
- At 1.1% (if the §8415(i) conditions are met): $90,000 × 1.1% × 4 = $3,960 a year.
Against the $7,575 deposit from the earlier example, that added annuity is paid every year of retirement (the two examples use separate illustrative figures) — and paying inside the two-year window keeps interest from adding to what those years cost.
If you are under CSRS
The Civil Service Retirement System rules run parallel, with three differences:
- A higher rate. §8334(j)(1)(A) sets the CSRS deposit at 7 percent of military basic pay paid. For service after December 31, 1998, §8334(j)(5) ties the percentage to the civilian rate in §8334(c) for the same period instead.
- A different start date for the window. The two-year interest-free period runs from the later of October 1, 1983 or your first federal employment after the service (§8334(j)(2)). §8334(e)(2) adds that interest runs from the mid-point of each service period included in the computation, and that “The deposit may be made in one or more installments.”
- The age-62 redetermination. Under §8332(c)(1), an employee first hired before October 1, 1982 is credited with military service subject to §8332(j). Under §8332(j)(1), military service after December 1956 (other than service covered by military leave with pay from a civilian position) is excluded from the annuity when the annuitant is entitled, or would on proper application be entitled, to monthly old-age or survivors benefits under 42 U.S.C. §402 based on their own wages — and if that entitlement arrives at 62, OPM redetermines the annuity from the first day of that month to exclude the service. §8332(j)(2)(A) exempts service for which the §8334(j) deposit was made. Employees first hired on or after October 1, 1982 are credited with post-1956 service only if the deposit is made (§8332(c)(1)(B)).
The retired-pay bar and its two exceptions are the same under CSRS (§8332(c)(2)), and so is the court-order rule (§8332(c)(4)).
What the WheelsUp Federal Buyback tool does
Federal Buyback is a Pro tool, and it puts the eligibility question first, because every dollar figure after it is meaningless on the wrong side of §8411(c)(2):
- Eligibility branch: not a military retiree, active-duty retired pay (waiver required, with the court-order note), Guard/Reserve retired pay, or combat or instrumentality-of-war disability retired pay. It starts from your profile and you can change it.
- Deposit principal: from the total military basic pay you enter off your own earnings records — 3% under FERS, with any 1999 and 2000 portions charged at 3.25% and 3.4%, or a flat 7% under CSRS.
- Interest: the year the interest-free window closes, from your first civilian year, and compounding over the number of years past it that you enter, at one annual rate you assume — labeled an estimate, because the real rate is set annually.
- The bought service in full years and months, from your profile's service dates. The tool cites the CSRS age-62 rule in its sources but does not compute it.
- What the years add: the annuity increase at 1% and at 1.1% of the federal average pay you assume, with the rate that applies to you marked, plus a rough break-even. A button hands that increase to the Lifetime Monte Carlo as a civilian pension from age 62, to be tested against simulated lifespans and COLA paths. The Monte Carlo adds that pension to your plan; it does not subtract military retired pay you would waive, so a retiree still weighs the waiver separately.
It does not model the interrupted-service cap, the post-1998 CSRS percentage, the §8415(h) reduction or survivor deposits, and it never tells you the deposit is worth it — that call is yours.
The short checklist
- Settle the §8411(c)(2) question first: no retired pay, Guard/Reserve retired pay, combat-related disability retired pay, or something else.
- Get your military basic pay figures for every period you want credited, including any 1999 and 2000 service.
- Note the date you started your federal job — the two-year interest-free window runs from it (or from January 1, 1987, if later).
- Pay the deposit in full through your employing agency before that window closes — a deposit made after it carries interest.
- If you have a former spouse with a court order against retired pay, read §8411(c)(5) before you waive anything.
- Estimate what the years add at 1% and, if you may qualify, 1.1% of your expected average pay.
Sources
- 5 U.S.C. §8411(c) — (1) credit for pre-1957 service and for post-1956 service with a §8422(e) deposit; (2) the retired-pay bar and the combat/instrumentality-of-war and chapter 1223 exceptions; (3) prior CSRS deposits; (4) survivor annuities; (5) waived retired pay subject to a §1408 court order
- 5 U.S.C. §8422(e) — (1)(A) 3 percent of military basic pay paid; (1)(B) the reemployment cap; (2) the two-year window and annual compounding at the §8334(e) rate; (3) remittance; (4) basic-pay information; (6) 3.25 percent for 1999 and 3.4 percent for 2000; (7) agency administrative error
- 5 U.S.C. §8334 — (e)(2) interest accrual, mid-point rule and installments; (e)(3) the interest rate; (j)(1)(A) the CSRS 7 percent deposit; (j)(2) the CSRS interest window; (j)(5) the post-1998 percentage
- 5 U.S.C. §8332 — (c)(1)–(2) and (c)(4) CSRS credit for military service; (j)(1)–(2)(A) the age-62 exclusion and the deposit exemption
- 5 U.S.C. §8415 — (a) 1 percent of average pay times total service; (h) the reduction before age 62 for §8412(g) and §8413(b) annuities; (i) the 1.1 percent rule and its exclusions
- 10 U.S.C. §12731 — the chapter 1223 entitlement and its eligibility age of 60
Spot an error? Tell us — citations are the product here.
A second pension is a decision, not a form. WheelsUp estimates your military retired pay, the deposit and what the years add — with the statute behind every line.